Attention: Please take a moment to consider our <a href="http://forum.charltonlife.com/home/termsofservice">terms and conditions</a> before posting.
Savings and Investments thread
Comments
-
Of course (Cash) ISA's work. There are hundreds of different products that are flexible, although wont be paying 4.5%- 5% I grant you. There are also lots you can have access to 3 times per year. I have one with Moneybox paying 4.4%.bobmunro said:
Is it bollocks. It is disproportionately hitting 20% rate pensioners who may have a small private pension and a relatively small amount of savings, or low wage earners trying to put a bit aside but may very well need to access the funds (so ISAs don't really work). That's not middle to high income earners.cantersaddick said:
Yeah it's ridiculous. If you look at who it's hitting as well, it's middle to high income earners with savings outside of ISA's. The same people who have been hit by various measures over the last decade. Instead of targeting the ultra rich or large corporations.bobmunro said:
In Tax Year 25/26 the rates of income tax on interest were 20%, 40% and 45%golfaddick said:
Its funny because I watched the Budget & heard him say an increase in tax to savings interest but don't think I heard an actual % amount.laurathered said: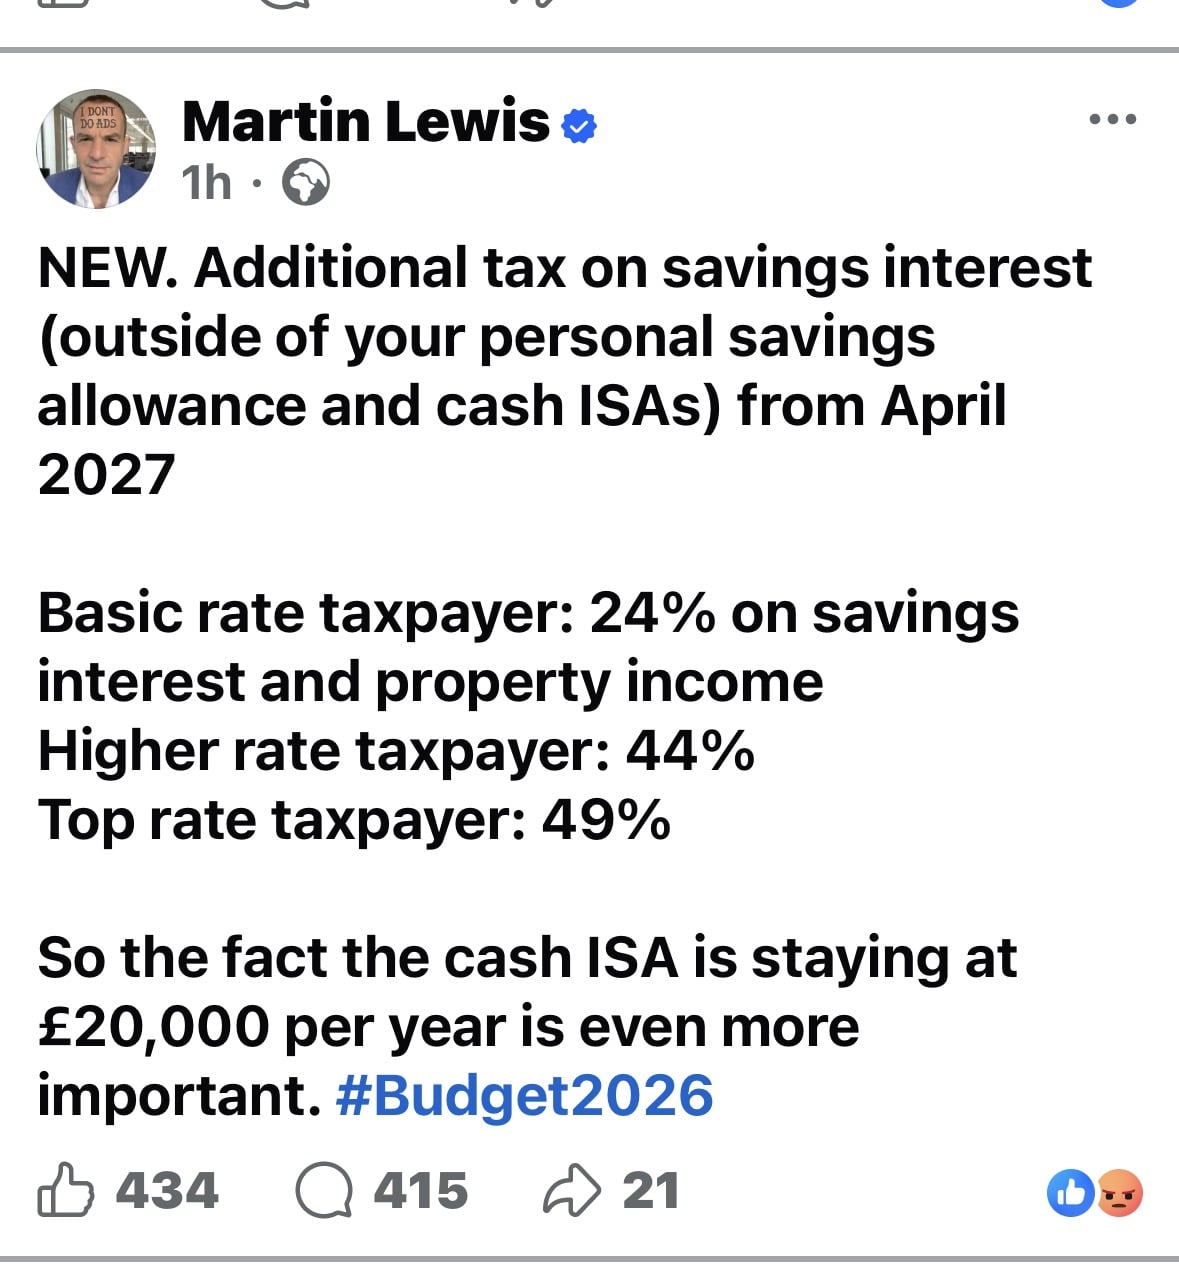
So you are paying more tax on your savings than you are on your income.
The Chancellor giveth & then takes it away.In Tax Year 26/27 the rates of income tax on interest were 22%, 42% and 47%In Tax Year 27/28 the rates of income tax on interest will be 24%, 44% and 49%So over two tax years basic rate tax payers see a 20% increase in the tax they pay on interest - 40% tax payers see a 10% increase in the tax they pay on interest, and 45% tax payers see a 8.9% increase in the tax they pay on interest.Not what you would call progressive tax policy, is it?
For all the talk of ending 40 years of Neoliberalism it was disappointingly just more of the same. Lots of tinkering, little give aways offset by little takes. Few good measures in the removal of standing charges and the bank levy. But that's about it. No structural changes to the tax system. Shame really. Missed opportunity but not surprised.
And basic rate taxpayers can get £1,000 interest before paying tax. At 4% that's £25k on deposit. And then there are Premium Bonds - max £50k.
So, a basic rate taxpayer can have almost £100k on deposit without paying tax.3 -
Came on to say I thought it was a very poor Budget. As pp said, it was just tinkering around the edges with no meaningful purpose.
Not getting political but I wonder what Labour voters think. There was all this hullabaloo with Andy Burnham becoming Labour leader & PM, spouting off all sorts about fresh starts & turning back the clock. And what do we get......£100 giveaways to some people & your Gas Standing Charge cancelled.
Is that all there is ????
Does make me think there will be a GE next year - around May I reckon.3 -
Felt like a treading water, don’t scare the horses, budget.5
-
I think the budget reveals just how much of a bind the PM and chancellor are in.I was impressed by it, because my fear was that post Starmer we would potentially end up with a 10 Downing Street that would destroy the finances of this country, and they definitely are not doing that which is a relief.
Perfect summary of where the finances of this nation are. The benefits system (including pensions) needs a complete overhaul. We need to get to a point where we are actually paying down the debt rather than clapping ourselves on the back for taxing a couple billion from banks and scattergunning £100 at homes in a pretty inefficient manner.blackpool72 said:Until the Labour cabinet stands up to their back benches and gets a grip on the ever increasing welfare and benefits we are fucked.
Like I said though, it could have been much, much worse.1 -
Is there any reason why the UK government doesn’t tax lottery winnings @ 50% like they do in USA? It feels like an obvious, easy and significant income earner that has zero negative impact on the individual who is still up £25m of the £50m they just won. It’s hardly going to dissuade the public from buying a ticket, is it?!1
-
If I remember correctly from 50 years ago when I did my economics degree, there is a lot of theory about the psychological impact on attitudes and behaviours of individuals once tax rates on income / savings move above 50%.bobmunro said:
In Tax Year 25/26 the rates of income tax on interest were 20%, 40% and 45%golfaddick said:
Its funny because I watched the Budget & heard him say an increase in tax to savings interest but don't think I heard an actual % amount.laurathered said:
So you are paying more tax on your savings than you are on your income.
The Chancellor giveth & then takes it away.In Tax Year 26/27 the rates of income tax on interest were 22%, 42% and 47%In Tax Year 27/28 the rates of income tax on interest will be 24%, 44% and 49%So over two tax years basic rate tax payers see a 20% increase in the tax they pay on interest - 40% tax payers see a 10% increase in the tax they pay on interest, and 45% tax payers see a 8.9% increase in the tax they pay on interest.Not what you would call progressive tax policy, is it?
0 -
Finally he’s seen the light on premium bonds 🤣golfaddick said:
Of course (Cash) ISA's work. There are hundreds of different products that are flexible, although wont be paying 4.5%- 5% I grant you. There are also lots you can have access to 3 times per year. I have one with Moneybox paying 4.4%.bobmunro said:
Is it bollocks. It is disproportionately hitting 20% rate pensioners who may have a small private pension and a relatively small amount of savings, or low wage earners trying to put a bit aside but may very well need to access the funds (so ISAs don't really work). That's not middle to high income earners.cantersaddick said:
Yeah it's ridiculous. If you look at who it's hitting as well, it's middle to high income earners with savings outside of ISA's. The same people who have been hit by various measures over the last decade. Instead of targeting the ultra rich or large corporations.bobmunro said:
In Tax Year 25/26 the rates of income tax on interest were 20%, 40% and 45%golfaddick said:
Its funny because I watched the Budget & heard him say an increase in tax to savings interest but don't think I heard an actual % amount.laurathered said:
So you are paying more tax on your savings than you are on your income.
The Chancellor giveth & then takes it away.In Tax Year 26/27 the rates of income tax on interest were 22%, 42% and 47%In Tax Year 27/28 the rates of income tax on interest will be 24%, 44% and 49%So over two tax years basic rate tax payers see a 20% increase in the tax they pay on interest - 40% tax payers see a 10% increase in the tax they pay on interest, and 45% tax payers see a 8.9% increase in the tax they pay on interest.Not what you would call progressive tax policy, is it?
For all the talk of ending 40 years of Neoliberalism it was disappointingly just more of the same. Lots of tinkering, little give aways offset by little takes. Few good measures in the removal of standing charges and the bank levy. But that's about it. No structural changes to the tax system. Shame really. Missed opportunity but not surprised.
And basic rate taxpayers can get £1,000 interest before paying tax. At 4% that's £25k on deposit. And then there are Premium Bonds - max £50k.
So, a basic rate taxpayer can have almost £100k on deposit without paying tax.
Realistically people who aren’t/weren’t major earners in their lives should have little taxable interest.
For a long while the ISA limit per year has been £20k. So unless you were saving more than that each year no reason to be paying much tax interest. Also plenty of flexible ISA’s you can transfer money into.
despite the above, still think the tax on savings levels are bonkers, as Bob has stated the increase is not progressive but either way, far too high.
but remember until 2016 all savings interest (outside of ISA’s etc) was all taxable, no savings allowance which at 5% allows £20k for a lower rate tax payer.
1 -
Bit of a nothing budget that. Personally was hoping they'd scrap stamp duty but that was wishful thinking1
-
Yes happily.Diebythesword said:
Would be interested to hear what makes this budget neoliberal?cantersaddick said:
Yeah it's ridiculous. If you look at who it's hitting as well, it's middle to high income earners with savings outside of ISA's. The same people who have been hit by various measures over the last decade. Instead of targeting the ultra rich or large corporations.bobmunro said:
In Tax Year 25/26 the rates of income tax on interest were 20%, 40% and 45%golfaddick said:
Its funny because I watched the Budget & heard him say an increase in tax to savings interest but don't think I heard an actual % amount.laurathered said:
So you are paying more tax on your savings than you are on your income.
The Chancellor giveth & then takes it away.In Tax Year 26/27 the rates of income tax on interest were 22%, 42% and 47%In Tax Year 27/28 the rates of income tax on interest will be 24%, 44% and 49%So over two tax years basic rate tax payers see a 20% increase in the tax they pay on interest - 40% tax payers see a 10% increase in the tax they pay on interest, and 45% tax payers see a 8.9% increase in the tax they pay on interest.Not what you would call progressive tax policy, is it?
For all the talk of ending 40 years of Neoliberalism it was disappointingly just more of the same. Lots of tinkering, little give aways offset by little takes. Few good measures in the removal of standing charges and the bank levy. But that's about it. No structural changes to the tax system. Shame really. Missed opportunity but not surprised.
So firstly its not that it the most neoliberal budget possible or that we've ever had its more that, as I said, for all the rhetoric of ending 40 years of neoliberalism it hasnt actually taken many if any steps to actually do that. It would probably be best described as neoliberal-lite. A softened version of the same thing rather than a clean break from it (which is what all the messaging was saying).
It has all been along the same lines and for the same goals; growth at all costs, in favour of big business, attempting to leverage financialisation and private equity rather than break from it and encourage the real functional economy, attempts to get private investment in public services etc.
Specifically:
- Exempting private equity hubs - this will largely benefit foreign based multinationals and the financialised sector.
-Corporate capital allowances increased - whilst badged as helping small start-ups the vast majority of this cash will go to established large corporations
- A series of deregulation moves
A whole bunch of moves to get private investors into public services:
- The NWF instead of directly building government owned infrastructure is only going to co-invest with private equity who will largely offshore profits.
- Mansion house accord it a financialised attempt to get private finance to modernise public adjacent sectors.
- Even the council house building announced isnt actually government directly building council houses its injecting the money into a state backed equity loan market which in effect gives direct support to the private banking sector.
There was some tinkering around the edges that they will try and badge as progress on this front but it was in the round tiny.
For me its more about what it didnt do than what it did. There were no steps to end privatisation, not even to start with the politically popular water sector as the obvious one, no steps to end monopolism or break up oligopoly power, no steps to remove corporate influence over government. Not even the scrapping of council tax & stamp duty for a LVT which has been much mooted and is pretty popular with the public. No real break from austerity (and anything that is badged as such is a temporary measure).0 -
Crypto: Reading today that Binance have lost billions to hackers but apparently can cover the losses.I don’t know if I’m impressed they have the means to do that or not.The industry remains a mystery to me as to how advocates see it as a replacement for traditional currency when hacking and dubious activity seems to dominate.5
-
Sponsored links:
-
I have probably missed something along the way on LISAs. I believe under the old system if you hadn't used it by 56 (or 10yesrs before state pension age) you could then take it all without penalty/tax. Can anybody confirm that this is still the case.golfaddick said:
Martin Lewis saying that if its nit used for a house purchase or the purchase price is above the limit then your LISA will be taxed at 20%, rather than 25%. You should, in theory, get back what you paid in - so no excess tax.superclive98 said:
Not as straightforward as scrapping it.golfaddick said:So......Good or Bad Budget. ?
Cash ISA's going to continue with the £20k allowance, dropping the plan to reduce it to £12k for the under 65's
Lifetime ISA's (LISA) to be replaced with a First Time Buyer ISA.& scrapping the penalty on the LISA if you dont use it for buying a house.0 -
Yep LISA is free when taking out when retired, thus the “lifetime” partredman said:
I have probably missed something along the way on LISAs. I believe under the old system if you hadn't used it by 56 (or 10yesrs before state pension age) you could then take it all without penalty/tax. Can anybody confirm that this is still the case.golfaddick said:
Martin Lewis saying that if its nit used for a house purchase or the purchase price is above the limit then your LISA will be taxed at 20%, rather than 25%. You should, in theory, get back what you paid in - so no excess tax.superclive98 said:
Not as straightforward as scrapping it.golfaddick said:So......Good or Bad Budget. ?
Cash ISA's going to continue with the £20k allowance, dropping the plan to reduce it to £12k for the under 65's
Lifetime ISA's (LISA) to be replaced with a First Time Buyer ISA.& scrapping the penalty on the LISA if you dont use it for buying a house.1 -
It's free at 60, isn't it?redman said:
I have probably missed something along the way on LISAs. I believe under the old system if you hadn't used it by 56 (or 10yesrs before state pension age) you could then take it all without penalty/tax. Can anybody confirm that this is still the case.golfaddick said:
Martin Lewis saying that if its nit used for a house purchase or the purchase price is above the limit then your LISA will be taxed at 20%, rather than 25%. You should, in theory, get back what you paid in - so no excess tax.superclive98 said:
Not as straightforward as scrapping it.golfaddick said:So......Good or Bad Budget. ?
Cash ISA's going to continue with the £20k allowance, dropping the plan to reduce it to £12k for the under 65's
Lifetime ISA's (LISA) to be replaced with a First Time Buyer ISA.& scrapping the penalty on the LISA if you dont use it for buying a house.
Before that it's deemed as an unauthorised withdrawal and so a penalty will be applied.1 -
Correct, 60 (currently) which is a bit bonkers when pensions are currently 55, moving to 57 in 18 months.superclive98 said:
It's free at 60, isn't it?redman said:
I have probably missed something along the way on LISAs. I believe under the old system if you hadn't used it by 56 (or 10yesrs before state pension age) you could then take it all without penalty/tax. Can anybody confirm that this is still the case.golfaddick said:
Martin Lewis saying that if its nit used for a house purchase or the purchase price is above the limit then your LISA will be taxed at 20%, rather than 25%. You should, in theory, get back what you paid in - so no excess tax.superclive98 said:
Not as straightforward as scrapping it.golfaddick said:So......Good or Bad Budget. ?
Cash ISA's going to continue with the £20k allowance, dropping the plan to reduce it to £12k for the under 65's
Lifetime ISA's (LISA) to be replaced with a First Time Buyer ISA.& scrapping the penalty on the LISA if you dont use it for buying a house.
Before that it's deemed as an unauthorised withdrawal and so a penalty will be applied.0 -
Lets see if they do cover the losses. The owner has two criminal convictions, but received a pardon from the orange gang-boss.valleynick66 said:Crypto: Reading today that Binance have lost billions to hackers but apparently can cover the losses.I don’t know if I’m impressed they have the means to do that or not.The industry remains a mystery to me as to how advocates see it as a replacement for traditional currency when hacking and dubious activity seems to dominate.
2 -
It's a good job everything is on the fully transparent blockchain. Should be no trouble at all to work out what was stolen and who the rightful owner is. Shouldn't it?PragueAddick said:
Lets see if they do cover the losses. The owner has two criminal convictions, but received a pardon from the orange gang-boss.valleynick66 said:Crypto: Reading today that Binance have lost billions to hackers but apparently can cover the losses.I don’t know if I’m impressed they have the means to do that or not.The industry remains a mystery to me as to how advocates see it as a replacement for traditional currency when hacking and dubious activity seems to dominate.8 -
No way they will cover any losses. This is akin to the Hatton garden robbery..... no one is going to pop up & declare that they had millions in Crypto & could they have it replaced please.PragueAddick said:
Lets see if they do cover the losses. The owner has two criminal convictions, but received a pardon from the orange gang-boss.valleynick66 said:Crypto: Reading today that Binance have lost billions to hackers but apparently can cover the losses.I don’t know if I’m impressed they have the means to do that or not.The industry remains a mystery to me as to how advocates see it as a replacement for traditional currency when hacking and dubious activity seems to dominate.0 -
In a different vein it was good to get Dan Neidle's view on the Budget on Peston on Wednesday night.
Great take on the new Pension Tax Allowance (you know, the jolly wheeze the Treasury have come up with to make sure anyone with pension income just above the Personal Allowance not to pay tax, even though any other person of the working population with the same income will). He said that the problem with this new Allowance is that it will now be around for ever. It will be increased year on year and/or tinkered with but ultimately will just become another tax allowance ' instead of just bloody increasing the PA for everyone. And this is how these things start. Like the actual Pension Allowance & the Lifetime Allowance (which although is now defunct still has the 25% TFC limit linked to it) that were brought in by Labour in 2006 and subsequently massively reduced under the Coalition in the name of austerity.4 -
Our tax system is over complicated and in my lifetime all successive governments have done is add to that complexity.golfaddick said:In a different vein it was good to get Dan Neidle's view on the Budget on Peston on Wednesday night.
Great take on the new Pension Tax Allowance (you know, the jolly wheeze the Treasury have come up with to make sure anyone with pension income just above the Personal Allowance not to pay tax, even though any other person of the working population with the same income will). He said that the problem with this new Allowance is that it will now be around for ever. It will be increased year on year and/or tinkered with but ultimately will just become another tax allowance ' instead of just bloody increasing the PA for everyone. And this is how these things start. Like the actual Pension Allowance & the Lifetime Allowance (which although is now defunct still has the 25% TFC limit linked to it) that were brought in by Labour in 2006 and subsequently massively reduced under the Coalition in the name of austerity.
It should be easy to have a single tax allowance that everyone has whether you earn £1 or £10m.
likewise get rid of NI for employees and have a single income tax (obviously various bands) at whatever rate is required.
its really not that difficult.
such as things like winter fuel allowance, just add it to the state pension or to the tax code so everyone receives.
The benefit system is also over complicated and surely could be simplified.
im sure there are huge cost savings to be had by simplifying all this.
8 -
Rob7Lee said:
Our tax system is over complicated and in my lifetime all successive governments have done is add to that complexity.golfaddick said:In a different vein it was good to get Dan Neidle's view on the Budget on Peston on Wednesday night.
Great take on the new Pension Tax Allowance (you know, the jolly wheeze the Treasury have come up with to make sure anyone with pension income just above the Personal Allowance not to pay tax, even though any other person of the working population with the same income will). He said that the problem with this new Allowance is that it will now be around for ever. It will be increased year on year and/or tinkered with but ultimately will just become another tax allowance ' instead of just bloody increasing the PA for everyone. And this is how these things start. Like the actual Pension Allowance & the Lifetime Allowance (which although is now defunct still has the 25% TFC limit linked to it) that were brought in by Labour in 2006 and subsequently massively reduced under the Coalition in the name of austerity.
It should be easy to have a single tax allowance that everyone has whether you earn £1 or £10m.
likewise get rid of NI for employees and have a single income tax (obviously various bands) at whatever rate is required.
its really not that difficult.
such as things like winter fuel allowance, just add it to the state pension or to the tax code so everyone receives.
The benefit system is also over complicated and surely could be simplified.
im sure there are huge cost savings to be had by simplifying all this.Agree with all of that.Like a lot of complex systems with bolt on amendments (held together with elastic bands) it becomes so messed up that they don't know where to start the process of change - so they don't bother.That, plus I'm not sure I would trust the government and/or HMRC to manage the back office software systems developments required.0 -
Sponsored links:
-
A classic example of why FT readers' comments are often a level above (certainly well above my pay grade)
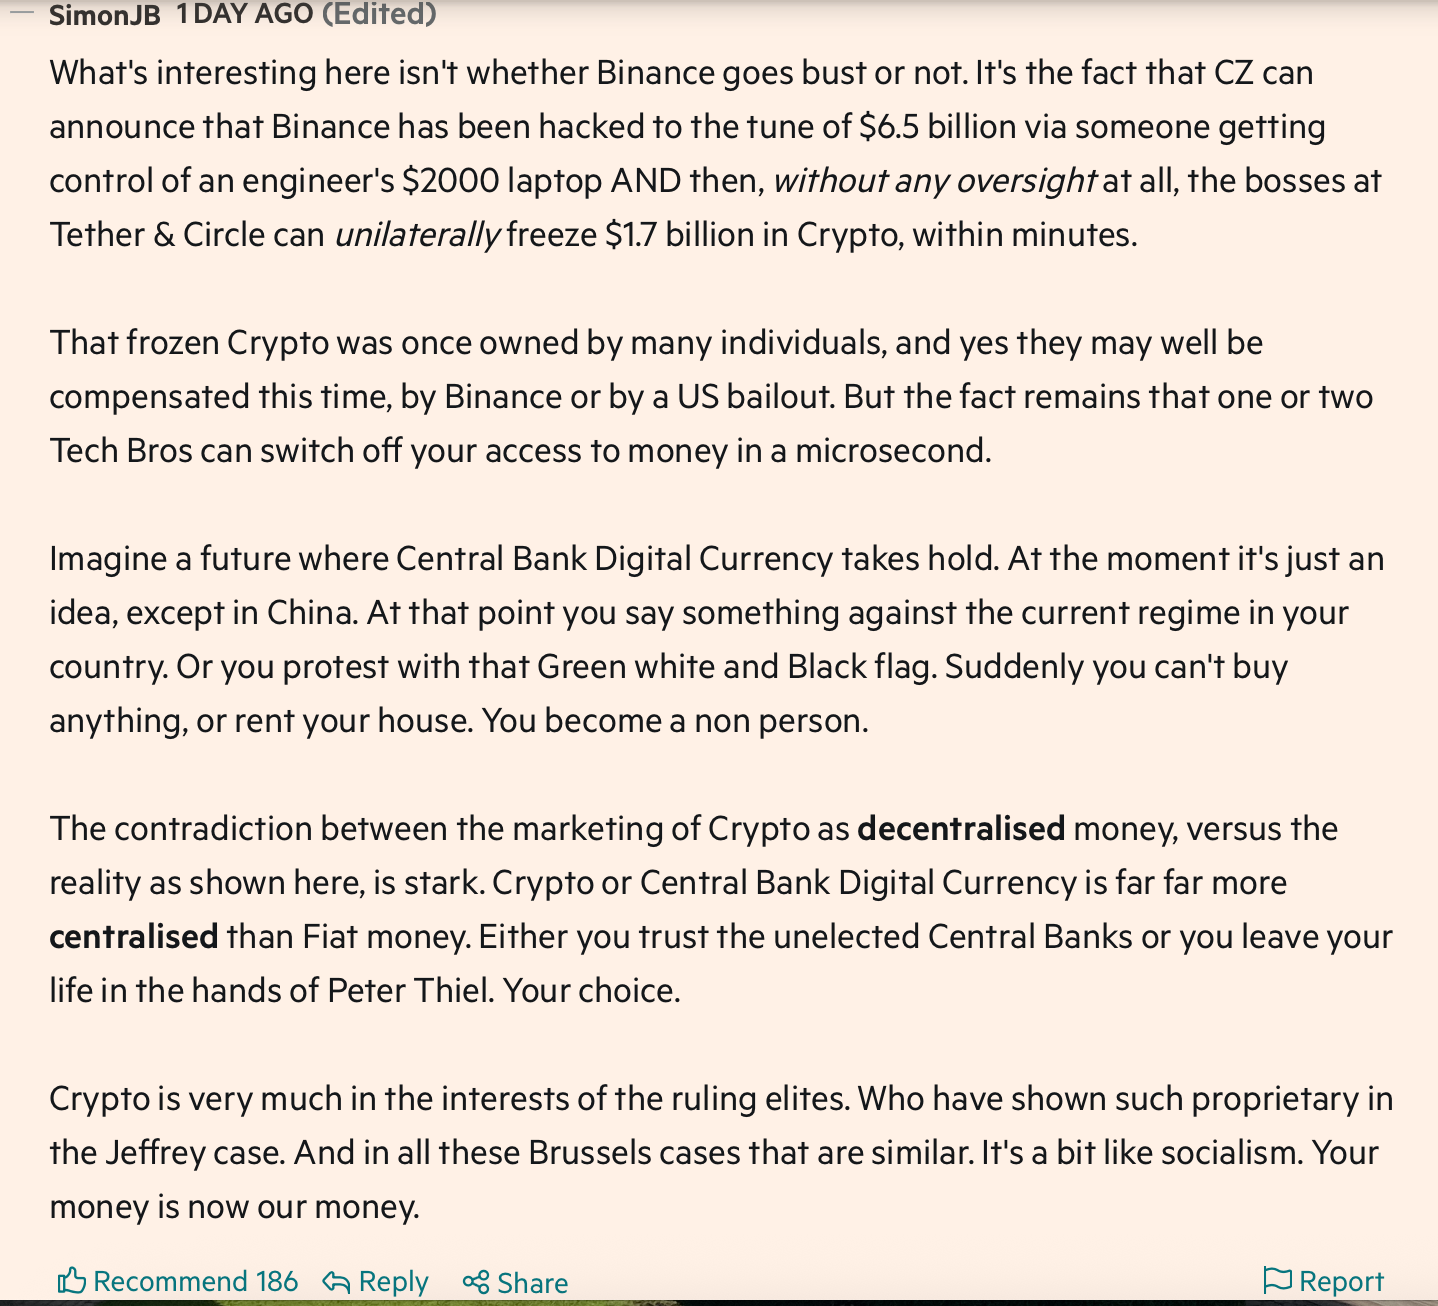 8
-
The cynical side of me says thats because the complexity fuels a whole other industry of incredibly well paid tax lawyers, advisors, dodgy accountants to find swerves and loopholes in a game of cat & mouse entirely of the governments making.
I personally see no reason in my simplistic utopian view that the whole system cannot be simplified as outlined by Rob7Lee above1 -
I mean, the comment is correct, but this was also a deliberate choice from lawmakers and the likes of the SEC and FCA. Tokenisation was always where the advantages to blockchain was anyway. But centralising it has been at every step of all crypto regulation.PragueAddick said:A classic example of why FT readers' comments are often a level above (certainly well above my pay grade)0 -
Yeah agree about simplification of the tax system. Was at a pre-budget talk by Helen Miller director of the IFS who described the last few decades of changes to the tax system as "Whack-a-mole". Every budget a change is made to take account for something or other (a break in business rates say) to pay for it they whack something else up. Both of them create some weird cliff edges and dodgy incentives which have to be corrected for at the next budget with more add ons and extras and so the cycle continues.Rob7Lee said:
Our tax system is over complicated and in my lifetime all successive governments have done is add to that complexity.golfaddick said:In a different vein it was good to get Dan Neidle's view on the Budget on Peston on Wednesday night.
Great take on the new Pension Tax Allowance (you know, the jolly wheeze the Treasury have come up with to make sure anyone with pension income just above the Personal Allowance not to pay tax, even though any other person of the working population with the same income will). He said that the problem with this new Allowance is that it will now be around for ever. It will be increased year on year and/or tinkered with but ultimately will just become another tax allowance ' instead of just bloody increasing the PA for everyone. And this is how these things start. Like the actual Pension Allowance & the Lifetime Allowance (which although is now defunct still has the 25% TFC limit linked to it) that were brought in by Labour in 2006 and subsequently massively reduced under the Coalition in the name of austerity.
It should be easy to have a single tax allowance that everyone has whether you earn £1 or £10m.
likewise get rid of NI for employees and have a single income tax (obviously various bands) at whatever rate is required.
its really not that difficult.
such as things like winter fuel allowance, just add it to the state pension or to the tax code so everyone receives.
The benefit system is also over complicated and surely could be simplified.
im sure there are huge cost savings to be had by simplifying all this.
This is so obvious. And uncontroversial. Which is why it's frustrating that it's not been addressed.3 -
I do not like cryptocurrencies at all, but worth noting that apparently Bitcoin and a few others cannot be frozen, at least in this case:PragueAddick said:A classic example of why FT readers' comments are often a level above (certainly well above my pay grade)"The remaining $3.3 billion is mostly Bitcoin, Ether, and XRP, which no one can freeze"1 -
Although I would agree with this the big problem would be the raft of winners and losers. Currently an employee below £50k pays 28% (20% IT plus 8% NI) whereas a pensioner (or landlord) pays 20%. I'm not going to argue the rights and wrongs or how we got to this point, but combinimg those 2 atm would not be politically possible.Rob7Lee said:
Our tax system is over complicated and in my lifetime all successive governments have done is add to that complexity.golfaddick said:In a different vein it was good to get Dan Neidle's view on the Budget on Peston on Wednesday night.
Great take on the new Pension Tax Allowance (you know, the jolly wheeze the Treasury have come up with to make sure anyone with pension income just above the Personal Allowance not to pay tax, even though any other person of the working population with the same income will). He said that the problem with this new Allowance is that it will now be around for ever. It will be increased year on year and/or tinkered with but ultimately will just become another tax allowance ' instead of just bloody increasing the PA for everyone. And this is how these things start. Like the actual Pension Allowance & the Lifetime Allowance (which although is now defunct still has the 25% TFC limit linked to it) that were brought in by Labour in 2006 and subsequently massively reduced under the Coalition in the name of austerity.
It should be easy to have a single tax allowance that everyone has whether you earn £1 or £10m.
likewise get rid of NI for employees and have a single income tax (obviously various bands) at whatever rate is required.
its really not that difficult.
such as things like winter fuel allowance, just add it to the state pension or to the tax code so everyone receives.
The benefit system is also over complicated and surely could be simplified.
im sure there are huge cost savings to be had by simplifying all this.0 -
I’m assuming NI on pensions might be part of the thinking for the mooted National Care Service.redman said:
Although I would agree with this the big problem would be the raft of winners and losers. Currently an employee below £50k pays 28% (20% IT plus 8% NI) whereas a pensioner (or landlord) pays 20%. I'm not going to argue the rights and wrongs or how we got to this point, but combinimg those 2 atm would not be politically possible.Rob7Lee said:
Our tax system is over complicated and in my lifetime all successive governments have done is add to that complexity.golfaddick said:In a different vein it was good to get Dan Neidle's view on the Budget on Peston on Wednesday night.
Great take on the new Pension Tax Allowance (you know, the jolly wheeze the Treasury have come up with to make sure anyone with pension income just above the Personal Allowance not to pay tax, even though any other person of the working population with the same income will). He said that the problem with this new Allowance is that it will now be around for ever. It will be increased year on year and/or tinkered with but ultimately will just become another tax allowance ' instead of just bloody increasing the PA for everyone. And this is how these things start. Like the actual Pension Allowance & the Lifetime Allowance (which although is now defunct still has the 25% TFC limit linked to it) that were brought in by Labour in 2006 and subsequently massively reduced under the Coalition in the name of austerity.
It should be easy to have a single tax allowance that everyone has whether you earn £1 or £10m.
likewise get rid of NI for employees and have a single income tax (obviously various bands) at whatever rate is required.
its really not that difficult.
such as things like winter fuel allowance, just add it to the state pension or to the tax code so everyone receives.
The benefit system is also over complicated and surely could be simplified.
im sure there are huge cost savings to be had by simplifying all this.0 -
Landlord is increasing to 24% from next April. But frankly it's ridiculous, there should be one 'income tax' whether you are retired or not, whether your income comes from 'working' or investing, having NI on (broadly) only those who get paid for their work is a little ridiculous, also on the self employed/lower rates. We are making it worse by giving some people a higher personal allowance simply by virtue of the idiots in charge making decisions like increasing the pension to a higher amount than the frozen personal allowance.redman said:
Although I would agree with this the big problem would be the raft of winners and losers. Currently an employee below £50k pays 28% (20% IT plus 8% NI) whereas a pensioner (or landlord) pays 20%. I'm not going to argue the rights and wrongs or how we got to this point, but combinimg those 2 atm would not be politically possible.Rob7Lee said:
Our tax system is over complicated and in my lifetime all successive governments have done is add to that complexity.golfaddick said:In a different vein it was good to get Dan Neidle's view on the Budget on Peston on Wednesday night.
Great take on the new Pension Tax Allowance (you know, the jolly wheeze the Treasury have come up with to make sure anyone with pension income just above the Personal Allowance not to pay tax, even though any other person of the working population with the same income will). He said that the problem with this new Allowance is that it will now be around for ever. It will be increased year on year and/or tinkered with but ultimately will just become another tax allowance ' instead of just bloody increasing the PA for everyone. And this is how these things start. Like the actual Pension Allowance & the Lifetime Allowance (which although is now defunct still has the 25% TFC limit linked to it) that were brought in by Labour in 2006 and subsequently massively reduced under the Coalition in the name of austerity.
It should be easy to have a single tax allowance that everyone has whether you earn £1 or £10m.
likewise get rid of NI for employees and have a single income tax (obviously various bands) at whatever rate is required.
its really not that difficult.
such as things like winter fuel allowance, just add it to the state pension or to the tax code so everyone receives.
The benefit system is also over complicated and surely could be simplified.
im sure there are huge cost savings to be had by simplifying all this.
Give everyone a Personal allowance (and it should be more than current, say £15-18k)
Change the tax rates to take into account NI being 'merged' in (so something like, 24%, 44%, 49% funnily enough)
Adjust the start/end point of the bands to adjust for the personal allowance increase
Move bands and the personal allowance annually in line with some form of inflation.
CGT align with Income tax.
Remove savings allowance (taken into account with the personal allowance)
Slowly work with industry to diminish the need for in work benefits, to me this was one of the worst things Labour did back in the 90's, we moved away from employers paying and moving it onto the state. Minimum wage should be more regional and be a lot higher in certain regions.
Overhaul the benefit system and bring it back to what it was meant to be, a short safety net (of course there are long term safety nets for disabled etc which should continue and probably go up).
5 -
Bonds tonight 00.001
-
This is so glaringly obvious to most of us it defies logic as to why no one ever does it.Rob7Lee said:
Landlord is increasing to 24% from next April. But frankly it's ridiculous, there should be one 'income tax' whether you are retired or not, whether your income comes from 'working' or investing, having NI on (broadly) only those who get paid for their work is a little ridiculous, also on the self employed/lower rates. We are making it worse by giving some people a higher personal allowance simply by virtue of the idiots in charge making decisions like increasing the pension to a higher amount than the frozen personal allowance.redman said:
Although I would agree with this the big problem would be the raft of winners and losers. Currently an employee below £50k pays 28% (20% IT plus 8% NI) whereas a pensioner (or landlord) pays 20%. I'm not going to argue the rights and wrongs or how we got to this point, but combinimg those 2 atm would not be politically possible.Rob7Lee said:
Our tax system is over complicated and in my lifetime all successive governments have done is add to that complexity.golfaddick said:In a different vein it was good to get Dan Neidle's view on the Budget on Peston on Wednesday night.
Great take on the new Pension Tax Allowance (you know, the jolly wheeze the Treasury have come up with to make sure anyone with pension income just above the Personal Allowance not to pay tax, even though any other person of the working population with the same income will). He said that the problem with this new Allowance is that it will now be around for ever. It will be increased year on year and/or tinkered with but ultimately will just become another tax allowance ' instead of just bloody increasing the PA for everyone. And this is how these things start. Like the actual Pension Allowance & the Lifetime Allowance (which although is now defunct still has the 25% TFC limit linked to it) that were brought in by Labour in 2006 and subsequently massively reduced under the Coalition in the name of austerity.
It should be easy to have a single tax allowance that everyone has whether you earn £1 or £10m.
likewise get rid of NI for employees and have a single income tax (obviously various bands) at whatever rate is required.
its really not that difficult.
such as things like winter fuel allowance, just add it to the state pension or to the tax code so everyone receives.
The benefit system is also over complicated and surely could be simplified.
im sure there are huge cost savings to be had by simplifying all this.
Give everyone a Personal allowance (and it should be more than current, say £15-18k)
Change the tax rates to take into account NI being 'merged' in (so something like, 24%, 44%, 49% funnily enough)
Adjust the start/end point of the bands to adjust for the personal allowance increase
Move bands and the personal allowance annually in line with some form of inflation.
CGT align with Income tax.
Remove savings allowance (taken into account with the personal allowance)
Slowly work with industry to diminish the need for in work benefits, to me this was one of the worst things Labour did back in the 90's, we moved away from employers paying and moving it onto the state. Minimum wage should be more regional and be a lot higher in certain regions.
Overhaul the benefit system and bring it back to what it was meant to be, a short safety net (of course there are long term safety nets for disabled etc which should continue and probably go up).Hard to see that most would not see it as fair and therefore a relatively easy sell.No idea of course what the financial modelling says would result.1