Savings and Investments thread
Comments
-
Ah - that makes much more sense. Thank you. The ‘help’ at the end of the phone was pretty bad tbhRob7Lee said:
Investec are good, I’m doing quite well on their shares and also in process of switching banking to them. But check as they refer to switching a cash ISA.bobmunro said:Arsenetatters said:I've got a S & S ISA with fidelity which I wanted to change to one of their 'ready made' S and S ISAs but am having trouble sorting it and each time I phone I get a different answer. I'm getting fed up with them so am thinking of transferring it to a cash ISA somewhere else. I've already used up this year's allowance but am I OK to transfer and still keep the tax benefits from this one?Edit - it's got over £20,000 in itTo build on @Rob7Lee you will probably have to sell your investments and convert them to cash before you can transfer the funds to a Cash ISA with another provider. Also, as you have already used up this year's allowance you need to open a Cash ISA elsewhere that doesn't require 'new' money in order to open it, just the transfer.Investec are offering 4.95% fixed for one year which is about the best out there at the moment - you can transfer in without needing new money to open it.(I mention Investec so much, anyone would think I;m on commission! They really are good though.)
On fidelity, answers these simple questions, note down the suggested fund and ‘switch’ what you have to that fund:
https://www.fidelity.co.uk/ready-made-isa/?ef_id=CjwKCAjw9PvWBhAxEiwAddzYyV6-io61jXH9Es53FtIdC4pLHWcJY_VowW8iI8wc7iG4N5jxG5J5KhoC8LkQAvD_BwE:G:s&s_kwcid=AL!8153!3!786808512429!p!!g!!fidelity%20ready-made%20isa!23328986789!191231735964&utm_source=google&utm_medium=paid_search&utm_campaign=uk_brand_2026_ready-made-isa_orders&gclsrc=aw.ds&gad_source=1&gad_campaignid=23328986789&gbraid=0AAAAAD_DS9f1x2ai3tLpEy32Pm3yL4mLI&gclid=CjwKCAjw9PvWBhAxEiwAddzYyV6-io61jXH9Es53FtIdC4pLHWcJY_VowW8iI8wc7iG4N5jxG5J5KhoC8LkQAvD_BwE0 -
What do we all think of the Budget "leak" that pensioners on just the Basic State Pension will have their Personal Allowance increased next April to £13036 so they wont be paying tax (around £100) on their State Pension Income.
And why are pensioners any different to a part time/ low paid earner who also has income of £13036 next year.
Why not just increase the PA to £13050 for everyone, instead of adding another level of faff.7 -
The usual madness, easiest is personal allowance to £13,050 and lower where the 40% band comes in by the equivalent increase. But that would mean a slightly lower tax take of course.golfaddick said:What do we all think of the Budget "leak" that pensioners on just the Basic State Pension will have their Personal Allowance increased next April to £13036 so they wont be paying tax (around £100) on their State Pension Income.
And why are pensioners any different to a part time/ low paid earner who also has income of £13036 next year.
Why not just increase the PA to £13050 for everyone, instead of adding another level of faff.
the way the bands have been frozen and the PA is a joke especially for the low earners.
but they are going to have this problem year after year. In another 5 years the pensioners who only get state pension will have an allowance nearing £20k.
im looking forward to retirement 🤣0 -
Labour are cnutsgolfaddick said:What do we all think of the Budget "leak" that pensioners on just the Basic State Pension will have their Personal Allowance increased next April to £13036 so they wont be paying tax (around £100) on their State Pension Income.
And why are pensioners any different to a part time/ low paid earner who also has income of £13036 next year.
Why not just increase the PA to £13050 for everyone, instead of adding another level of faff.
That's. My educated view4 -
I'm a better off pensioner. But what I find a little bit annpoying is that I elected to pay extra into a company pension and opened my own SIPP. So the fact I have additional pension income is because I decided to forgo some income for the sake of the future. I know people who opted out of pension schemes and now rely on state pension so they are, in effect, rewarded! I'm not bitter about it as I'm, relatively speaking, comfortable but it does seem a bit unfair - any increased PA should apply to all of pension age.4
-
Sadly it's the same with all 'means tested' stuff. It's measured at a point in time, not how frugal or wasteful you have been. Time we got rid of pretty much all benefits and just paid every adult from 18 to death a (very) basic wage.CafcWest said:I'm a better off pensioner. But what I find a little bit annpoying is that I elected to pay extra into a company pension and opened my own SIPP. So the fact I have additional pension income is because I decided to forgo some income for the sake of the future. I know people who opted out of pension schemes and now rely on state pension so they are, in effect, rewarded! I'm not bitter about it as I'm, relatively speaking, comfortable but it does seem a bit unfair - any increased PA should apply to all of pension age.3 -
Rob7Lee said:
Investec are good, I’m doing quite well on their shares and also in process of switching banking to them. But check as they refer to switching a cash ISA.bobmunro said:Arsenetatters said:I've got a S & S ISA with fidelity which I wanted to change to one of their 'ready made' S and S ISAs but am having trouble sorting it and each time I phone I get a different answer. I'm getting fed up with them so am thinking of transferring it to a cash ISA somewhere else. I've already used up this year's allowance but am I OK to transfer and still keep the tax benefits from this one?Edit - it's got over £20,000 in itTo build on @Rob7Lee you will probably have to sell your investments and convert them to cash before you can transfer the funds to a Cash ISA with another provider. Also, as you have already used up this year's allowance you need to open a Cash ISA elsewhere that doesn't require 'new' money in order to open it, just the transfer.Investec are offering 4.95% fixed for one year which is about the best out there at the moment - you can transfer in without needing new money to open it.(I mention Investec so much, anyone would think I;m on commission! They really are good though.)
On fidelity, answers these simple questions, note down the suggested fund and ‘switch’ what you have to that fund:
https://www.fidelity.co.uk/ready-made-isa/?ef_id=CjwKCAjw9PvWBhAxEiwAddzYyV6-io61jXH9Es53FtIdC4pLHWcJY_VowW8iI8wc7iG4N5jxG5J5KhoC8LkQAvD_BwE:G:s&s_kwcid=AL!8153!3!786808512429!p!!g!!fidelity%20ready-made%20isa!23328986789!191231735964&utm_source=google&utm_medium=paid_search&utm_campaign=uk_brand_2026_ready-made-isa_orders&gclsrc=aw.ds&gad_source=1&gad_campaignid=23328986789&gbraid=0AAAAAD_DS9f1x2ai3tLpEy32Pm3yL4mLI&gclid=CjwKCAjw9PvWBhAxEiwAddzYyV6-io61jXH9Es53FtIdC4pLHWcJY_VowW8iI8wc7iG4N5jxG5J5KhoC8LkQAvD_BwEIt's fine as long as the transfer is in cash. I sold a lump of MMFs and transferred it to Investec from a SS ISA. Open the fixed rate Cash ISA with Investec first and then during the application stage indicate that you are transferring from another provider. Let them have the details of your existing provider, account number and amount and they will do the rest.2 -
One thing I meant to check, the fixed rate ISA - they appear to pay out the interest to your linked account at maturity, so you lose that tax free wrapper for the interest, not a problem if you are spending it, but worth knowing for those who want to build not spend.bobmunro said:Rob7Lee said:
Investec are good, I’m doing quite well on their shares and also in process of switching banking to them. But check as they refer to switching a cash ISA.bobmunro said:Arsenetatters said:I've got a S & S ISA with fidelity which I wanted to change to one of their 'ready made' S and S ISAs but am having trouble sorting it and each time I phone I get a different answer. I'm getting fed up with them so am thinking of transferring it to a cash ISA somewhere else. I've already used up this year's allowance but am I OK to transfer and still keep the tax benefits from this one?Edit - it's got over £20,000 in itTo build on @Rob7Lee you will probably have to sell your investments and convert them to cash before you can transfer the funds to a Cash ISA with another provider. Also, as you have already used up this year's allowance you need to open a Cash ISA elsewhere that doesn't require 'new' money in order to open it, just the transfer.Investec are offering 4.95% fixed for one year which is about the best out there at the moment - you can transfer in without needing new money to open it.(I mention Investec so much, anyone would think I;m on commission! They really are good though.)
On fidelity, answers these simple questions, note down the suggested fund and ‘switch’ what you have to that fund:
https://www.fidelity.co.uk/ready-made-isa/?ef_id=CjwKCAjw9PvWBhAxEiwAddzYyV6-io61jXH9Es53FtIdC4pLHWcJY_VowW8iI8wc7iG4N5jxG5J5KhoC8LkQAvD_BwE:G:s&s_kwcid=AL!8153!3!786808512429!p!!g!!fidelity%20ready-made%20isa!23328986789!191231735964&utm_source=google&utm_medium=paid_search&utm_campaign=uk_brand_2026_ready-made-isa_orders&gclsrc=aw.ds&gad_source=1&gad_campaignid=23328986789&gbraid=0AAAAAD_DS9f1x2ai3tLpEy32Pm3yL4mLI&gclid=CjwKCAjw9PvWBhAxEiwAddzYyV6-io61jXH9Es53FtIdC4pLHWcJY_VowW8iI8wc7iG4N5jxG5J5KhoC8LkQAvD_BwEIt's fine as long as the transfer is in cash. I sold a lump of MMFs and transferred it to Investec from a SS ISA. Open the fixed rate Cash ISA with Investec first and then during the application stage indicate that you are transferring from another provider. Let them have the details of your existing provider, account number and amount and they will do the rest.3 -
Rob7Lee said:
One thing I meant to check, the fixed rate ISA - they appear to pay out the interest to your linked account at maturity, so you lose that tax free wrapper for the interest, not a problem if you are spending it, but worth knowing for those who want to build not spend.bobmunro said:Rob7Lee said:
Investec are good, I’m doing quite well on their shares and also in process of switching banking to them. But check as they refer to switching a cash ISA.bobmunro said:Arsenetatters said:I've got a S & S ISA with fidelity which I wanted to change to one of their 'ready made' S and S ISAs but am having trouble sorting it and each time I phone I get a different answer. I'm getting fed up with them so am thinking of transferring it to a cash ISA somewhere else. I've already used up this year's allowance but am I OK to transfer and still keep the tax benefits from this one?Edit - it's got over £20,000 in itTo build on @Rob7Lee you will probably have to sell your investments and convert them to cash before you can transfer the funds to a Cash ISA with another provider. Also, as you have already used up this year's allowance you need to open a Cash ISA elsewhere that doesn't require 'new' money in order to open it, just the transfer.Investec are offering 4.95% fixed for one year which is about the best out there at the moment - you can transfer in without needing new money to open it.(I mention Investec so much, anyone would think I;m on commission! They really are good though.)
On fidelity, answers these simple questions, note down the suggested fund and ‘switch’ what you have to that fund:
https://www.fidelity.co.uk/ready-made-isa/?ef_id=CjwKCAjw9PvWBhAxEiwAddzYyV6-io61jXH9Es53FtIdC4pLHWcJY_VowW8iI8wc7iG4N5jxG5J5KhoC8LkQAvD_BwE:G:s&s_kwcid=AL!8153!3!786808512429!p!!g!!fidelity%20ready-made%20isa!23328986789!191231735964&utm_source=google&utm_medium=paid_search&utm_campaign=uk_brand_2026_ready-made-isa_orders&gclsrc=aw.ds&gad_source=1&gad_campaignid=23328986789&gbraid=0AAAAAD_DS9f1x2ai3tLpEy32Pm3yL4mLI&gclid=CjwKCAjw9PvWBhAxEiwAddzYyV6-io61jXH9Es53FtIdC4pLHWcJY_VowW8iI8wc7iG4N5jxG5J5KhoC8LkQAvD_BwEIt's fine as long as the transfer is in cash. I sold a lump of MMFs and transferred it to Investec from a SS ISA. Open the fixed rate Cash ISA with Investec first and then during the application stage indicate that you are transferring from another provider. Let them have the details of your existing provider, account number and amount and they will do the rest.Very good point.At my age I'm spending it, but if longer term growth is the strategy then a provider with compounding of interest is preferred.0 -
So......Good or Bad Budget. ?
Cash ISA's going to continue with the £20k allowance, dropping the plan to reduce it to £12k for the under 65's
Lifetime ISA's (LISA) to be replaced with a First Time Buyer ISA.& scrapping the penalty on the LISA if you dont use it for buying a house.
1 -
Sponsored links:
-
Cash ISA limit to stay at £20K rather than being reduced to £12k, as proposed by the previous div.0
-
Still think ISAs need to be simplified and have one type of isa, all providers must provide a minimum range of low cost index funds to invest in. So they’re essentially stocks and shares isa and automatically earn interest on the cash in them. The fact they’re now both going to be £20k limit makes this make even more sense.0
-
I might be alone in this
I get maybe disproportionately angry with every budget delivered and the patronising way politiicans get enthused about saving "normal people" £100 a year off an energy bill that is so disgustingly expensive because of politicans or minute hand outs that will have no tangible impact in anyone's life but in black and white they can say they have given instead of taken.
Another opportunity missed to simplify the tax system instead adding more layers to it ignored. Too difficult.
To encourage investment that ridiculous CGT threshold needs to be increased
Inheritance tax disgusts me and that isn't a tax likely to ever affect me. Same as stamp duty
Sensible making the cash ISA limit back to what it was, great. Displays what a lummox the previous Chancellor was that this gimp has immediately reversed it
None of the budget encourages people to spend money. The CGT means people sit on winning investments and drip gains out rather than taking a £30k win and spending it
1 -
That's the last thing they want !!! Jeez.....interest rates will be through the roof if you actually got the economy going. Its not doing much at the moment & interest rates are set to rise next week.Carter said:I might be alone in this
None of the budget encourages people to spend money. The CGT means people sit on winning investments and drip gains out rather than taking a £30k win and spending it
(Yes, thats me being facetious - see my posts last week re inflation & the rate rise just around the corner)1 -
Until the Labour cabinet stands up to their back benches and gets a grip on the ever increasing welfare and benefits we are fucked.9
-
Imagine the pile on if ME14 made a comment like this.blackpool72 said:Until the Labour cabinet stands up to their back benches and gets a grip on the ever increasing welfare and benefits we are fucked.6 -
1 -
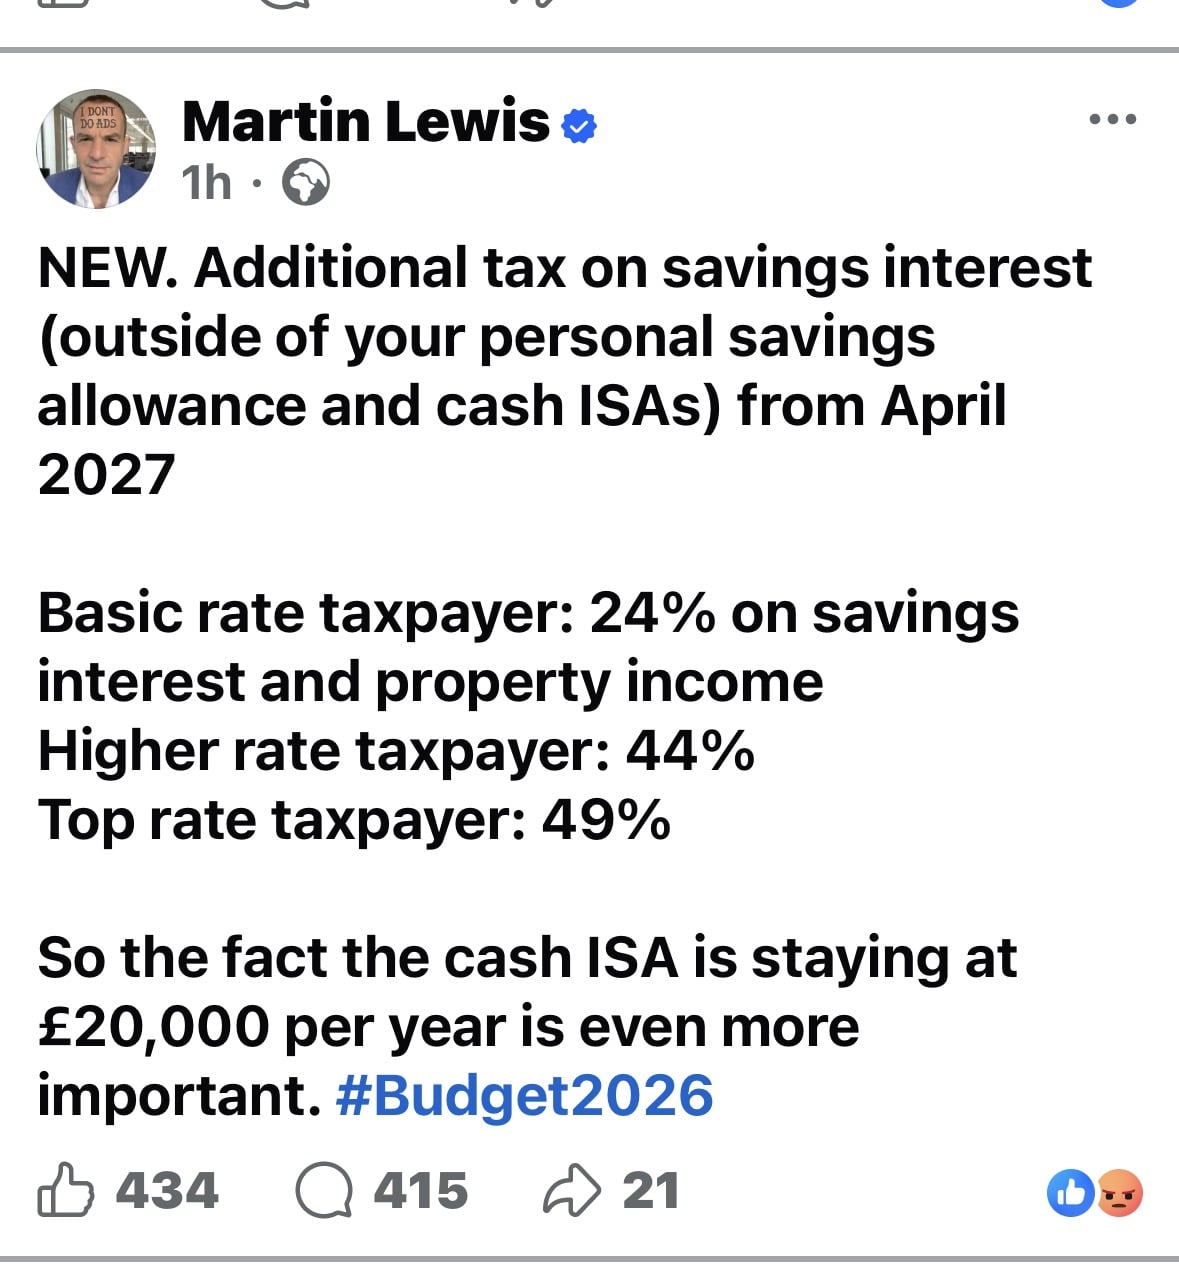
Its funny because I watched the Budget & heard him say an increase in tax to savings interest but don't think I heard an actual % amount.laurathered said:
So you are paying more tax on your savings than you are on your income.
The Chancellor giveth & then takes it away.0 -
Anyone know if you hold cash in a S&S ISA whether it will be taxed from next April as planned by Rachel from accounts or has that brainwave also been dropped?0
-
I've not heard anything but I would expect it to have been dropped if you can still hold £20k in a Cash ISA.Fortune 82nd Minute said:Anyone know if you hold cash in a S&S ISA whether it will be taxed from next April as planned by Rachel from accounts or has that brainwave also been dropped?
Edit
Seen Martin Lewis is saying it's all been scrapped. Good policy that one Rachel 👍🙄0 -
Sponsored links:
-
Not as straightforward as scrapping it.golfaddick said:So......Good or Bad Budget. ?
Cash ISA's going to continue with the £20k allowance, dropping the plan to reduce it to £12k for the under 65's
Lifetime ISA's (LISA) to be replaced with a First Time Buyer ISA.& scrapping the penalty on the LISA if you dont use it for buying a house.0 -
In Tax Year 25/26 the rates of income tax on interest were 20%, 40% and 45%golfaddick said:
Its funny because I watched the Budget & heard him say an increase in tax to savings interest but don't think I heard an actual % amount.laurathered said:
So you are paying more tax on your savings than you are on your income.
The Chancellor giveth & then takes it away.In Tax Year 26/27 the rates of income tax on interest were 22%, 42% and 47%In Tax Year 27/28 the rates of income tax on interest will be 24%, 44% and 49%So over two tax years basic rate tax payers see a 20% increase in the tax they pay on interest - 40% tax payers see a 10% increase in the tax they pay on interest, and 45% tax payers see a 8.9% increase in the tax they pay on interest.Not what you would call progressive tax policy, is it?7 -
Seems strange to tax bank account interest more than earned income. Get those ISA’s filled up!!bobmunro said:
In Tax Year 25/26 the rates of income tax on interest were 20%, 40% and 45%golfaddick said:
Its funny because I watched the Budget & heard him say an increase in tax to savings interest but don't think I heard an actual % amount.laurathered said:
So you are paying more tax on your savings than you are on your income.
The Chancellor giveth & then takes it away.In Tax Year 26/27 the rates of income tax on interest were 22%, 42% and 47%In Tax Year 27/28 the rates of income tax on interest will be 24%, 44% and 49%So over two tax years basic rate tax payers see a 20% increase in the tax they pay on interest - 40% tax payers see a 10% increase in the tax they pay on interest, and 45% tax payers see a 8.9% increase in the tax they pay on interest.Not what you would call progressive tax policy, is it?0 -
Martin Lewis saying that if its nit used for a house purchase or the purchase price is above the limit then your LISA will be taxed at 20%, rather than 25%. You should, in theory, get back what you paid in - so no excess tax.superclive98 said:
Not as straightforward as scrapping it.golfaddick said:So......Good or Bad Budget. ?
Cash ISA's going to continue with the £20k allowance, dropping the plan to reduce it to £12k for the under 65's
Lifetime ISA's (LISA) to be replaced with a First Time Buyer ISA.& scrapping the penalty on the LISA if you dont use it for buying a house.1 -
Yeah it's ridiculous. If you look at who it's hitting as well, it's middle to high income earners with savings outside of ISA's. The same people who have been hit by various measures over the last decade. Instead of targeting the ultra rich or large corporations.bobmunro said:
In Tax Year 25/26 the rates of income tax on interest were 20%, 40% and 45%golfaddick said:
Its funny because I watched the Budget & heard him say an increase in tax to savings interest but don't think I heard an actual % amount.laurathered said:
So you are paying more tax on your savings than you are on your income.
The Chancellor giveth & then takes it away.In Tax Year 26/27 the rates of income tax on interest were 22%, 42% and 47%In Tax Year 27/28 the rates of income tax on interest will be 24%, 44% and 49%So over two tax years basic rate tax payers see a 20% increase in the tax they pay on interest - 40% tax payers see a 10% increase in the tax they pay on interest, and 45% tax payers see a 8.9% increase in the tax they pay on interest.Not what you would call progressive tax policy, is it?
For all the talk of ending 40 years of Neoliberalism it was disappointingly just more of the same. Lots of tinkering, little give aways offset by little takes. Few good measures in the removal of standing charges and the bank levy. But that's about it. No structural changes to the tax system. Shame really. Missed opportunity but not surprised.0 -
Would be interested to hear what makes this budget neoliberal?cantersaddick said:
Yeah it's ridiculous. If you look at who it's hitting as well, it's middle to high income earners with savings outside of ISA's. The same people who have been hit by various measures over the last decade. Instead of targeting the ultra rich or large corporations.bobmunro said:
In Tax Year 25/26 the rates of income tax on interest were 20%, 40% and 45%golfaddick said:
Its funny because I watched the Budget & heard him say an increase in tax to savings interest but don't think I heard an actual % amount.laurathered said:
So you are paying more tax on your savings than you are on your income.
The Chancellor giveth & then takes it away.In Tax Year 26/27 the rates of income tax on interest were 22%, 42% and 47%In Tax Year 27/28 the rates of income tax on interest will be 24%, 44% and 49%So over two tax years basic rate tax payers see a 20% increase in the tax they pay on interest - 40% tax payers see a 10% increase in the tax they pay on interest, and 45% tax payers see a 8.9% increase in the tax they pay on interest.Not what you would call progressive tax policy, is it?
For all the talk of ending 40 years of Neoliberalism it was disappointingly just more of the same. Lots of tinkering, little give aways offset by little takes. Few good measures in the removal of standing charges and the bank levy. But that's about it. No structural changes to the tax system. Shame really. Missed opportunity but not surprised.0 -
Is it bollocks. It is disproportionately hitting 20% rate pensioners who may have a small private pension and a relatively small amount of savings, or low wage earners trying to put a bit aside but may very well need to access the funds (so ISAs don't really work). That's not middle to high income earners.cantersaddick said:
Yeah it's ridiculous. If you look at who it's hitting as well, it's middle to high income earners with savings outside of ISA's. The same people who have been hit by various measures over the last decade. Instead of targeting the ultra rich or large corporations.bobmunro said:
In Tax Year 25/26 the rates of income tax on interest were 20%, 40% and 45%golfaddick said:
Its funny because I watched the Budget & heard him say an increase in tax to savings interest but don't think I heard an actual % amount.laurathered said:
So you are paying more tax on your savings than you are on your income.
The Chancellor giveth & then takes it away.In Tax Year 26/27 the rates of income tax on interest were 22%, 42% and 47%In Tax Year 27/28 the rates of income tax on interest will be 24%, 44% and 49%So over two tax years basic rate tax payers see a 20% increase in the tax they pay on interest - 40% tax payers see a 10% increase in the tax they pay on interest, and 45% tax payers see a 8.9% increase in the tax they pay on interest.Not what you would call progressive tax policy, is it?
For all the talk of ending 40 years of Neoliberalism it was disappointingly just more of the same. Lots of tinkering, little give aways offset by little takes. Few good measures in the removal of standing charges and the bank levy. But that's about it. No structural changes to the tax system. Shame really. Missed opportunity but not surprised.
4 -
Hardly makes saving worthwhile ... I've always saved 20% or more of salary. After you max out your ISA then, as a higher rate tax payer, then 44% (very nearly half) will go in tax - that's crazy...no incentive to save ...bobmunro said:
In Tax Year 25/26 the rates of income tax on interest were 20%, 40% and 45%golfaddick said:
Its funny because I watched the Budget & heard him say an increase in tax to savings interest but don't think I heard an actual % amount.laurathered said:
So you are paying more tax on your savings than you are on your income.
The Chancellor giveth & then takes it away.In Tax Year 26/27 the rates of income tax on interest were 22%, 42% and 47%In Tax Year 27/28 the rates of income tax on interest will be 24%, 44% and 49%So over two tax years basic rate tax payers see a 20% increase in the tax they pay on interest - 40% tax payers see a 10% increase in the tax they pay on interest, and 45% tax payers see a 8.9% increase in the tax they pay on interest.Not what you would call progressive tax policy, is it?3 -
Thats what I can't wrap my brain around. Every incentive should be there for everyone to do as much as they personally can so as not to be a burden on the state yet if you manage to save enough to make that a viable option the state stick their useless fingers into it.
1 -
Fair point. Hadn't considered that point. Though will still those who max out their ISA's but need liquidity of savings too.bobmunro said:
Is it bollocks. It is disproportionately hitting 20% rate pensioners who may have a small private pension and a relatively small amount of savings, or low wage earners trying to put a bit aside but may very well need to access the funds (so ISAs don't really work). That's not middle to high income earners.cantersaddick said:
Yeah it's ridiculous. If you look at who it's hitting as well, it's middle to high income earners with savings outside of ISA's. The same people who have been hit by various measures over the last decade. Instead of targeting the ultra rich or large corporations.bobmunro said:
In Tax Year 25/26 the rates of income tax on interest were 20%, 40% and 45%golfaddick said:
Its funny because I watched the Budget & heard him say an increase in tax to savings interest but don't think I heard an actual % amount.laurathered said:
So you are paying more tax on your savings than you are on your income.
The Chancellor giveth & then takes it away.In Tax Year 26/27 the rates of income tax on interest were 22%, 42% and 47%In Tax Year 27/28 the rates of income tax on interest will be 24%, 44% and 49%So over two tax years basic rate tax payers see a 20% increase in the tax they pay on interest - 40% tax payers see a 10% increase in the tax they pay on interest, and 45% tax payers see a 8.9% increase in the tax they pay on interest.Not what you would call progressive tax policy, is it?
For all the talk of ending 40 years of Neoliberalism it was disappointingly just more of the same. Lots of tinkering, little give aways offset by little takes. Few good measures in the removal of standing charges and the bank levy. But that's about it. No structural changes to the tax system. Shame really. Missed opportunity but not surprised.1